Equities Risk
Correlations Among Selected Observable Factors
Correlation diagnostics for factor-mimicking portfolio returns, used to identify overlap among economic, style and statistical factors.
Synopsis
Here we present the rank-correlations of the factor mimicking portfolio (FMP) returns for the shortlisted subset of observable factors, selected for their ability to capture systematic return variation. The purpose is to determine the extent to which apparently distinct factors are capturing similar return variation. High absolute correlations suggest overlapping exposures, while low correlations suggest more distinct sources of risk.
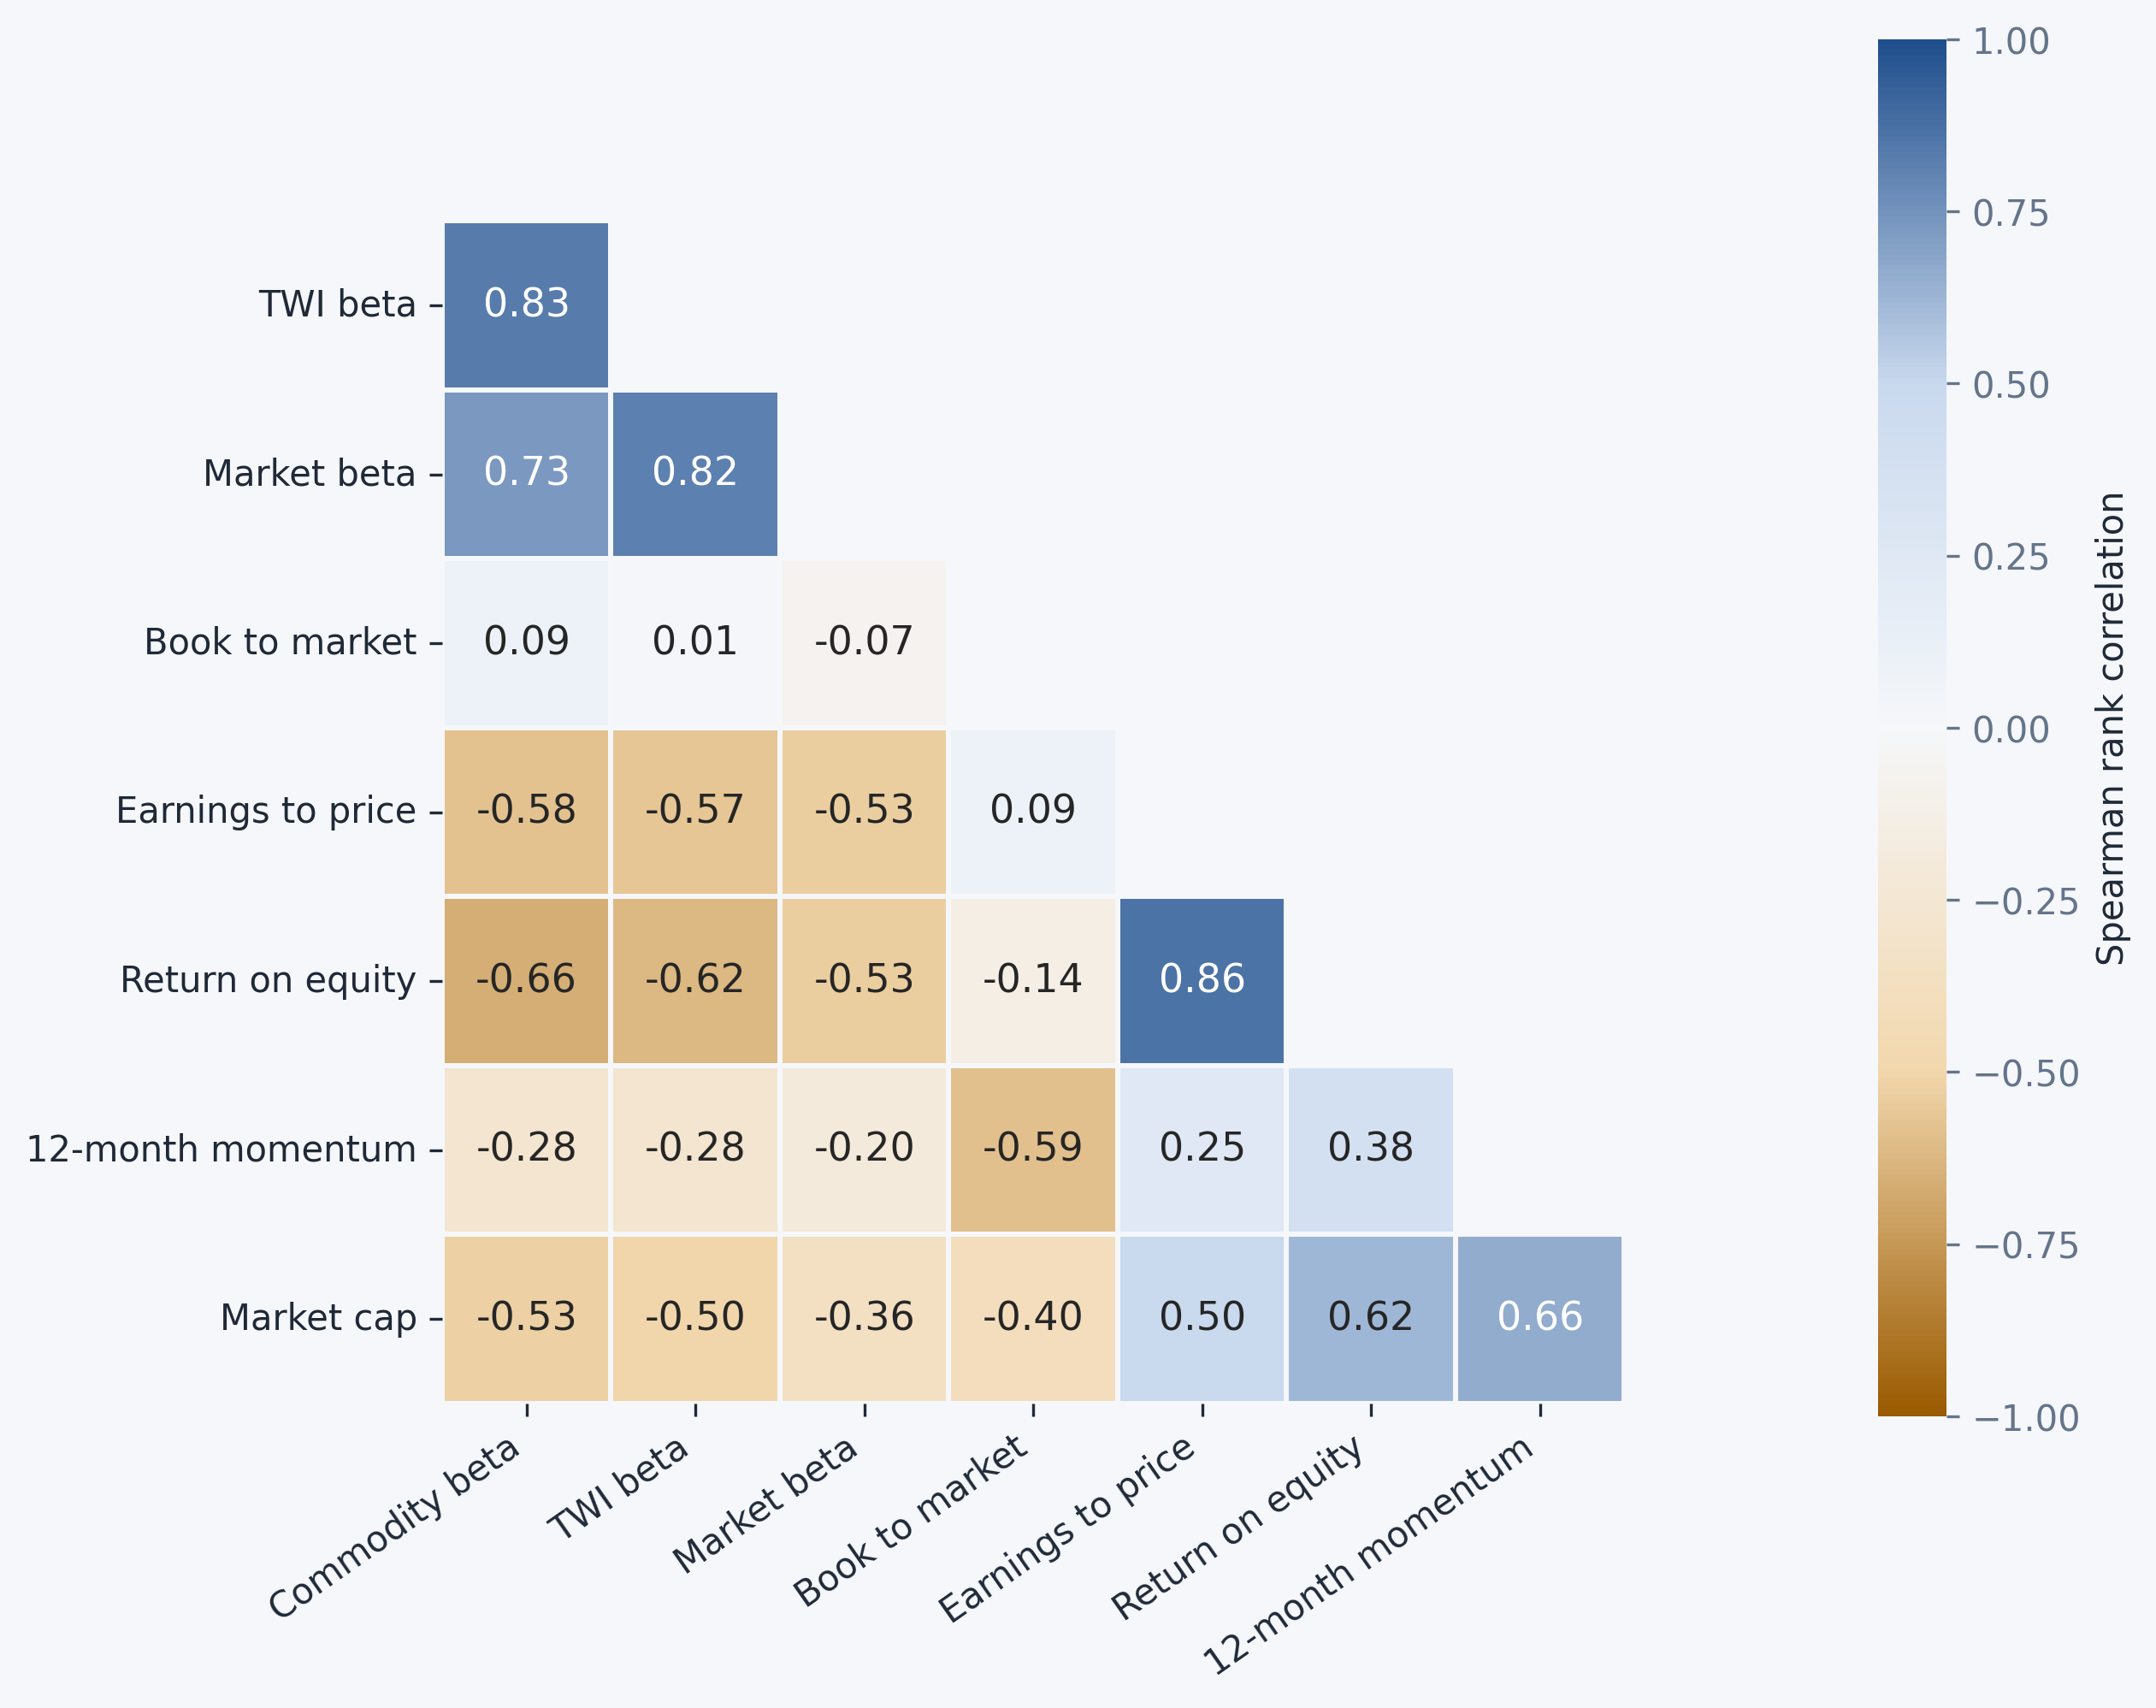
The selected observable factors exhibit several clear clusters of common variation. The three macro sensitivities, commodity beta, TWI beta and market beta, are strongly positively correlated with one another, with correlations ranging from 0.73 to 0.83. Earnings-to-price and return on equity also form a particularly strong pair (0.86), and both are negatively correlated with the macro betas. The strength of the relationship may partly be due to the shared net income numerator. Market capitalisation is positively associated with earnings-to-price, return on equity and momentum, while being negatively related to each of the macro sensitivities. These relationships suggest that, despite representing economically distinct concepts, several of the selected factors contain substantial overlapping information.
Book-to-market is a notable exception. It is essentially uncorrelated with the macro betas and only weakly related to earnings-to-price and return on equity, despite often being grouped with earnings-to-price as a value measure. Its strongest relationship is instead a negative correlation with 12-month momentum (-0.59), followed by market capitalisation (-0.40). Overall, the heatmap indicates that the shortlisted factor set spans several distinct dimensions of firm characteristics and systematic exposure, but also highlights areas of potentially important redundancy, most clearly among the macro betas and between earnings-to-price and return on equity.