Equities Risk
Latent factor structure across rolling 5-year windows
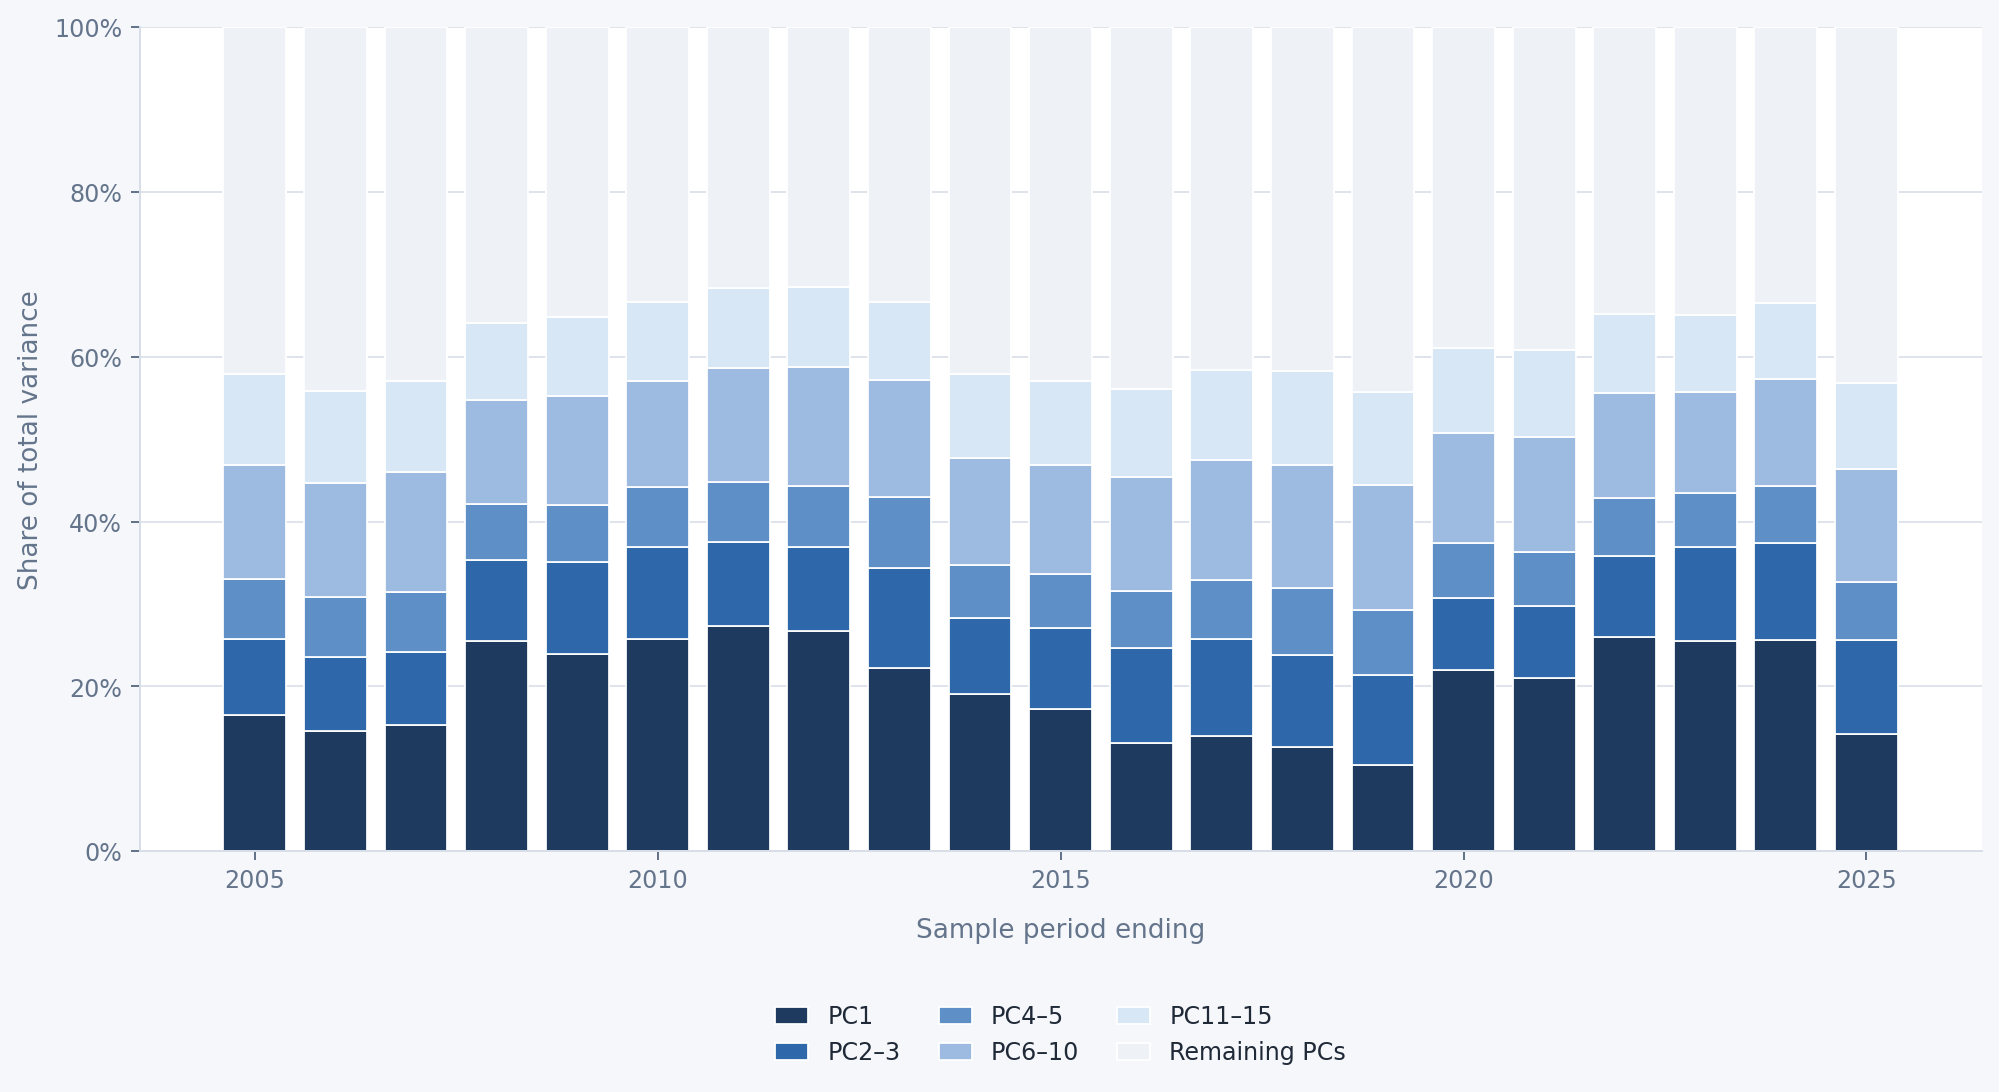
Principal-component analysis of Australian equity returns, showing the stability of latent factor structure through time.
Purpose
This section attempts to provide a rough guide to the number of latent factors in the Australian equity market at different levels of required explanatory power, and also examines the stability of that number over time.
Methodology
Every December, principal components analysis is applied to the constituents of the All Ordinaries Index using monthly equity returns over the previous five-year window. Each bar represents the variance decomposition for the five years ending December of the year on the horizontal axis.
Interpretation
The appropriate number of factors depends on the level of explanatory power required. A small number of factors captures the dominant sources of common variation, but even achieving 60% explanatory power requires including many additional components. The results highlight the trade-off between model simplicity and explanatory power, particularly in a relatively small equity universe.