Equities Risk
Optimal Number of Statistical Factors
A principal-components analysis estimating the number of latent statistical factors in Australian equity returns.
Purpose
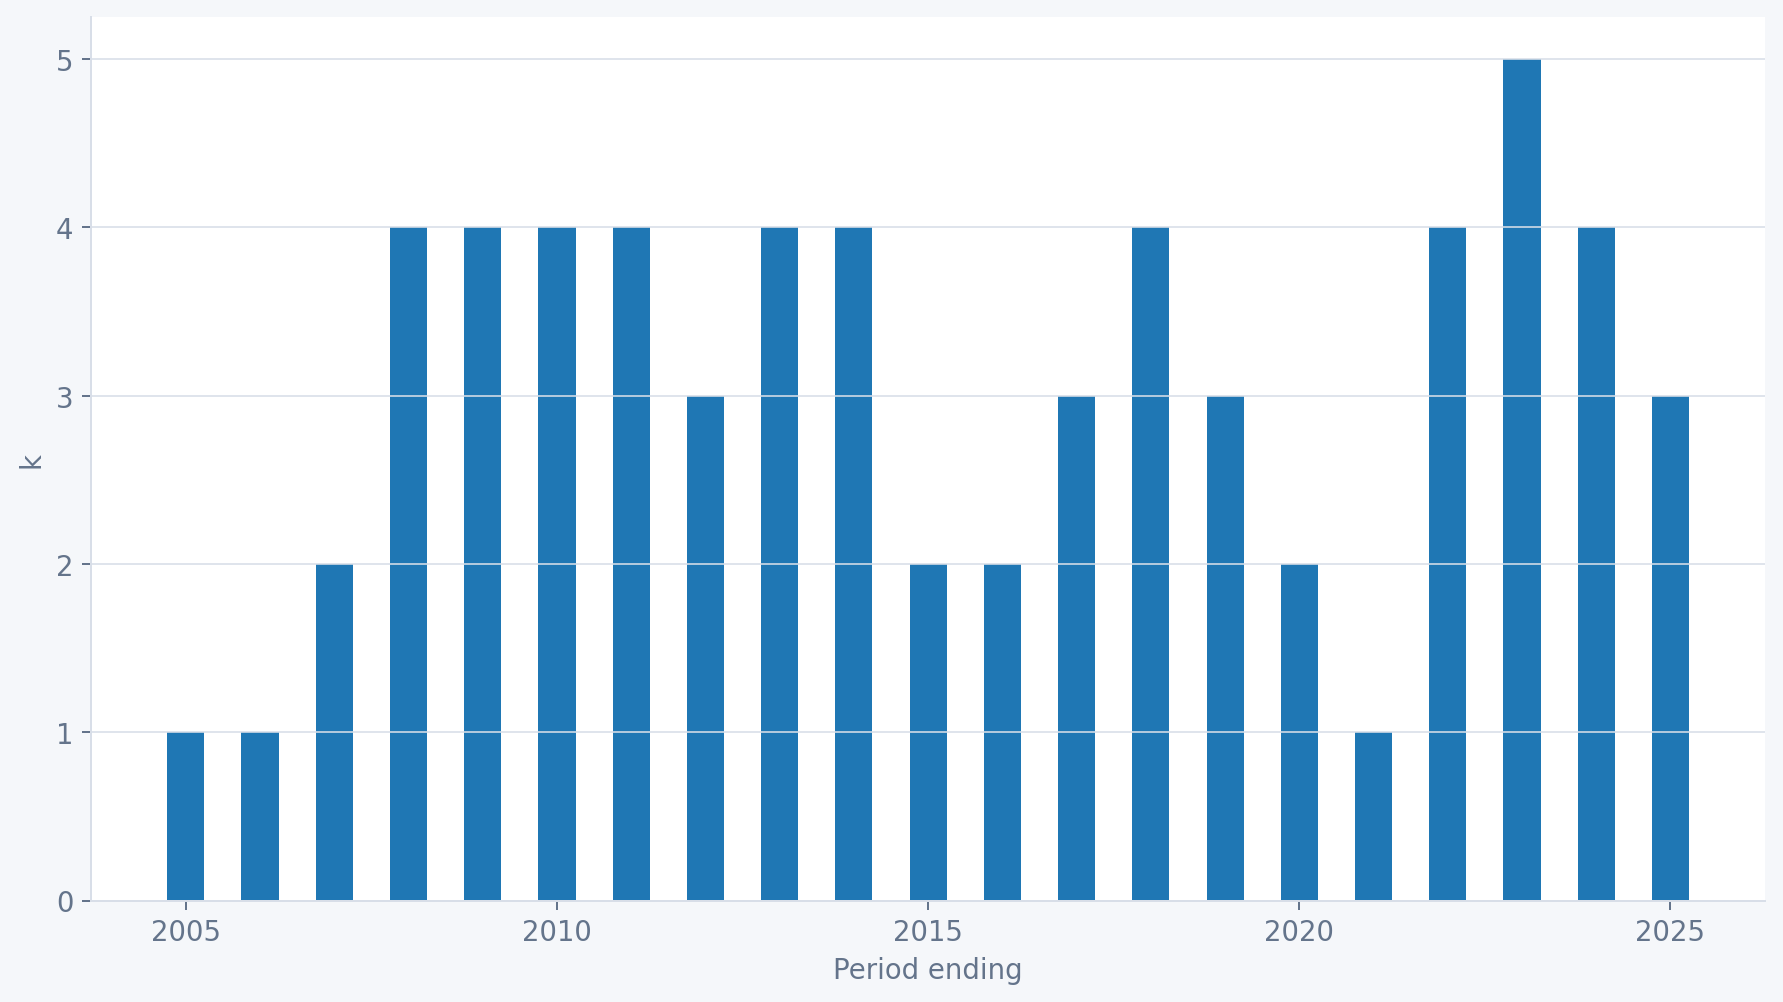
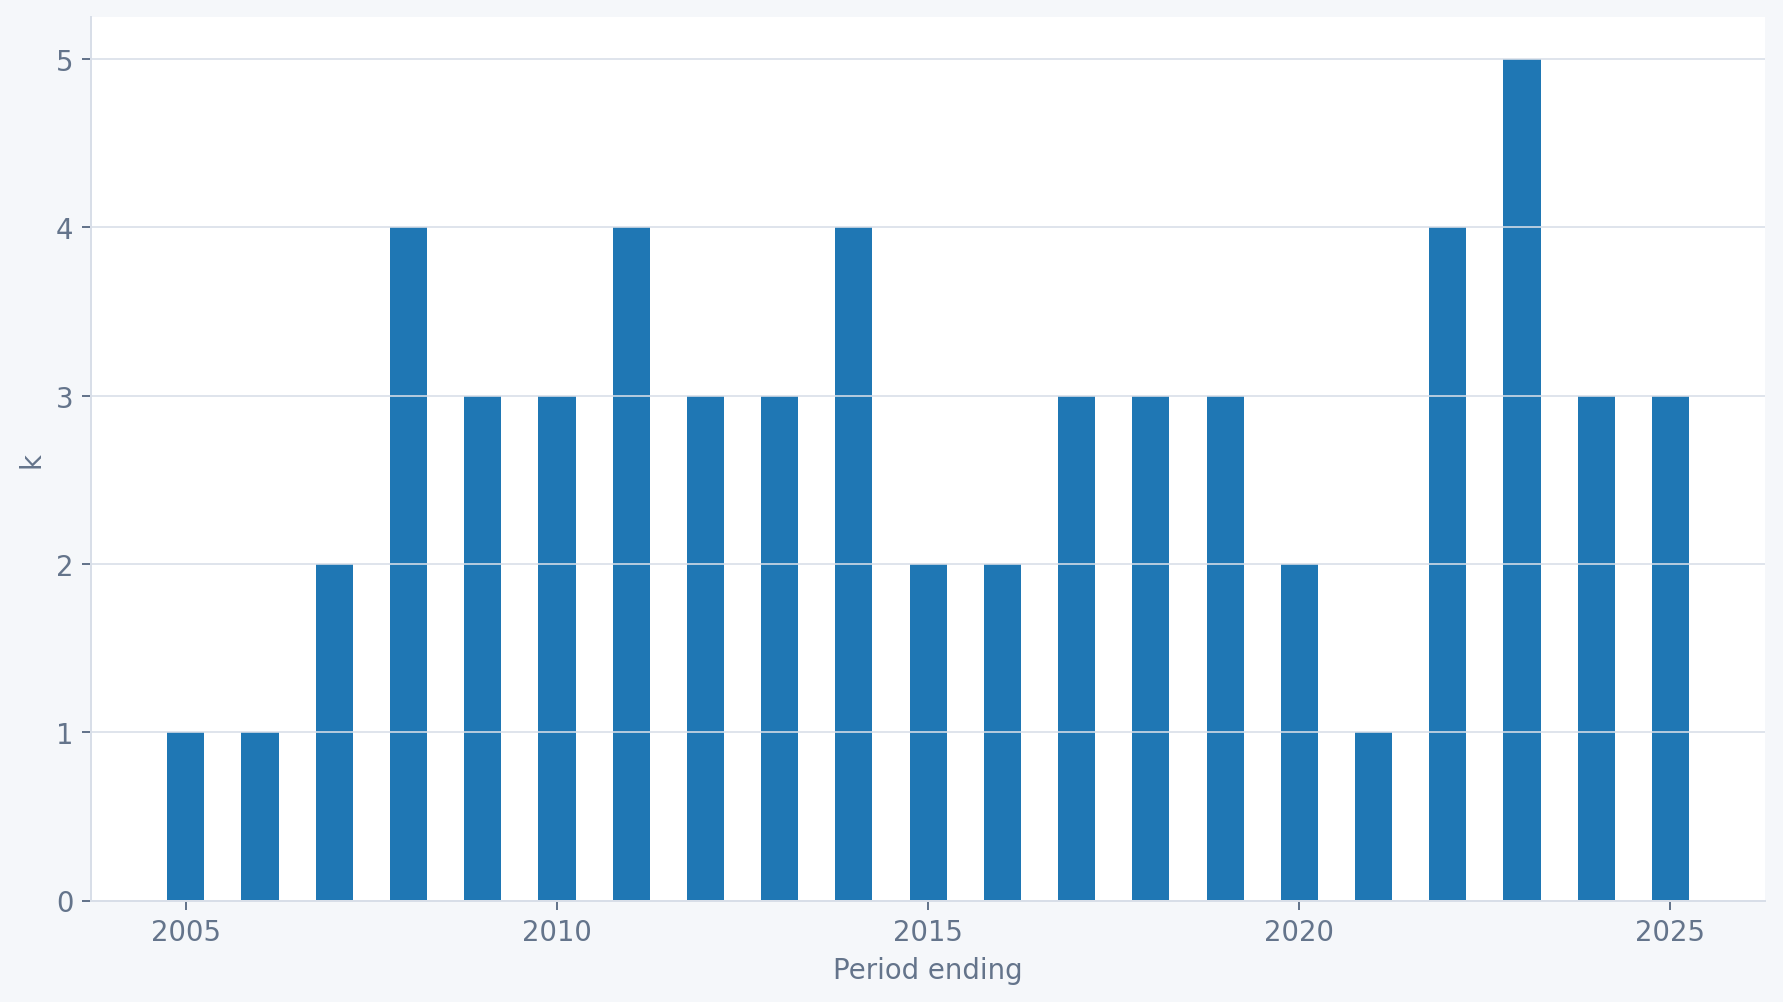
This page examines the number of latent statistical factors needed to summarise common variation in returns for the Australian equities market. This diagnostic uses information criteria proposed by Bai and Ng (2002), applied to rolling five-year return panels.
Interpretation
Lower values of each criterion indicate a more favourable balance between explanatory power and model complexity. The selected number of factors is the value that minimises the respective criterion. Based on the analyses, we estimate a maximum of four statistical factors, to be considered in risk models alongside observable factors like firm attributes, loadings on economic factors, and industry membership.