Equities Risk
Factor-industry correlations (market-purged returns)
Diagnostics to identify the extent of any overlap between factor and industry returns, after the effect of the market has been removed.
Synopsis
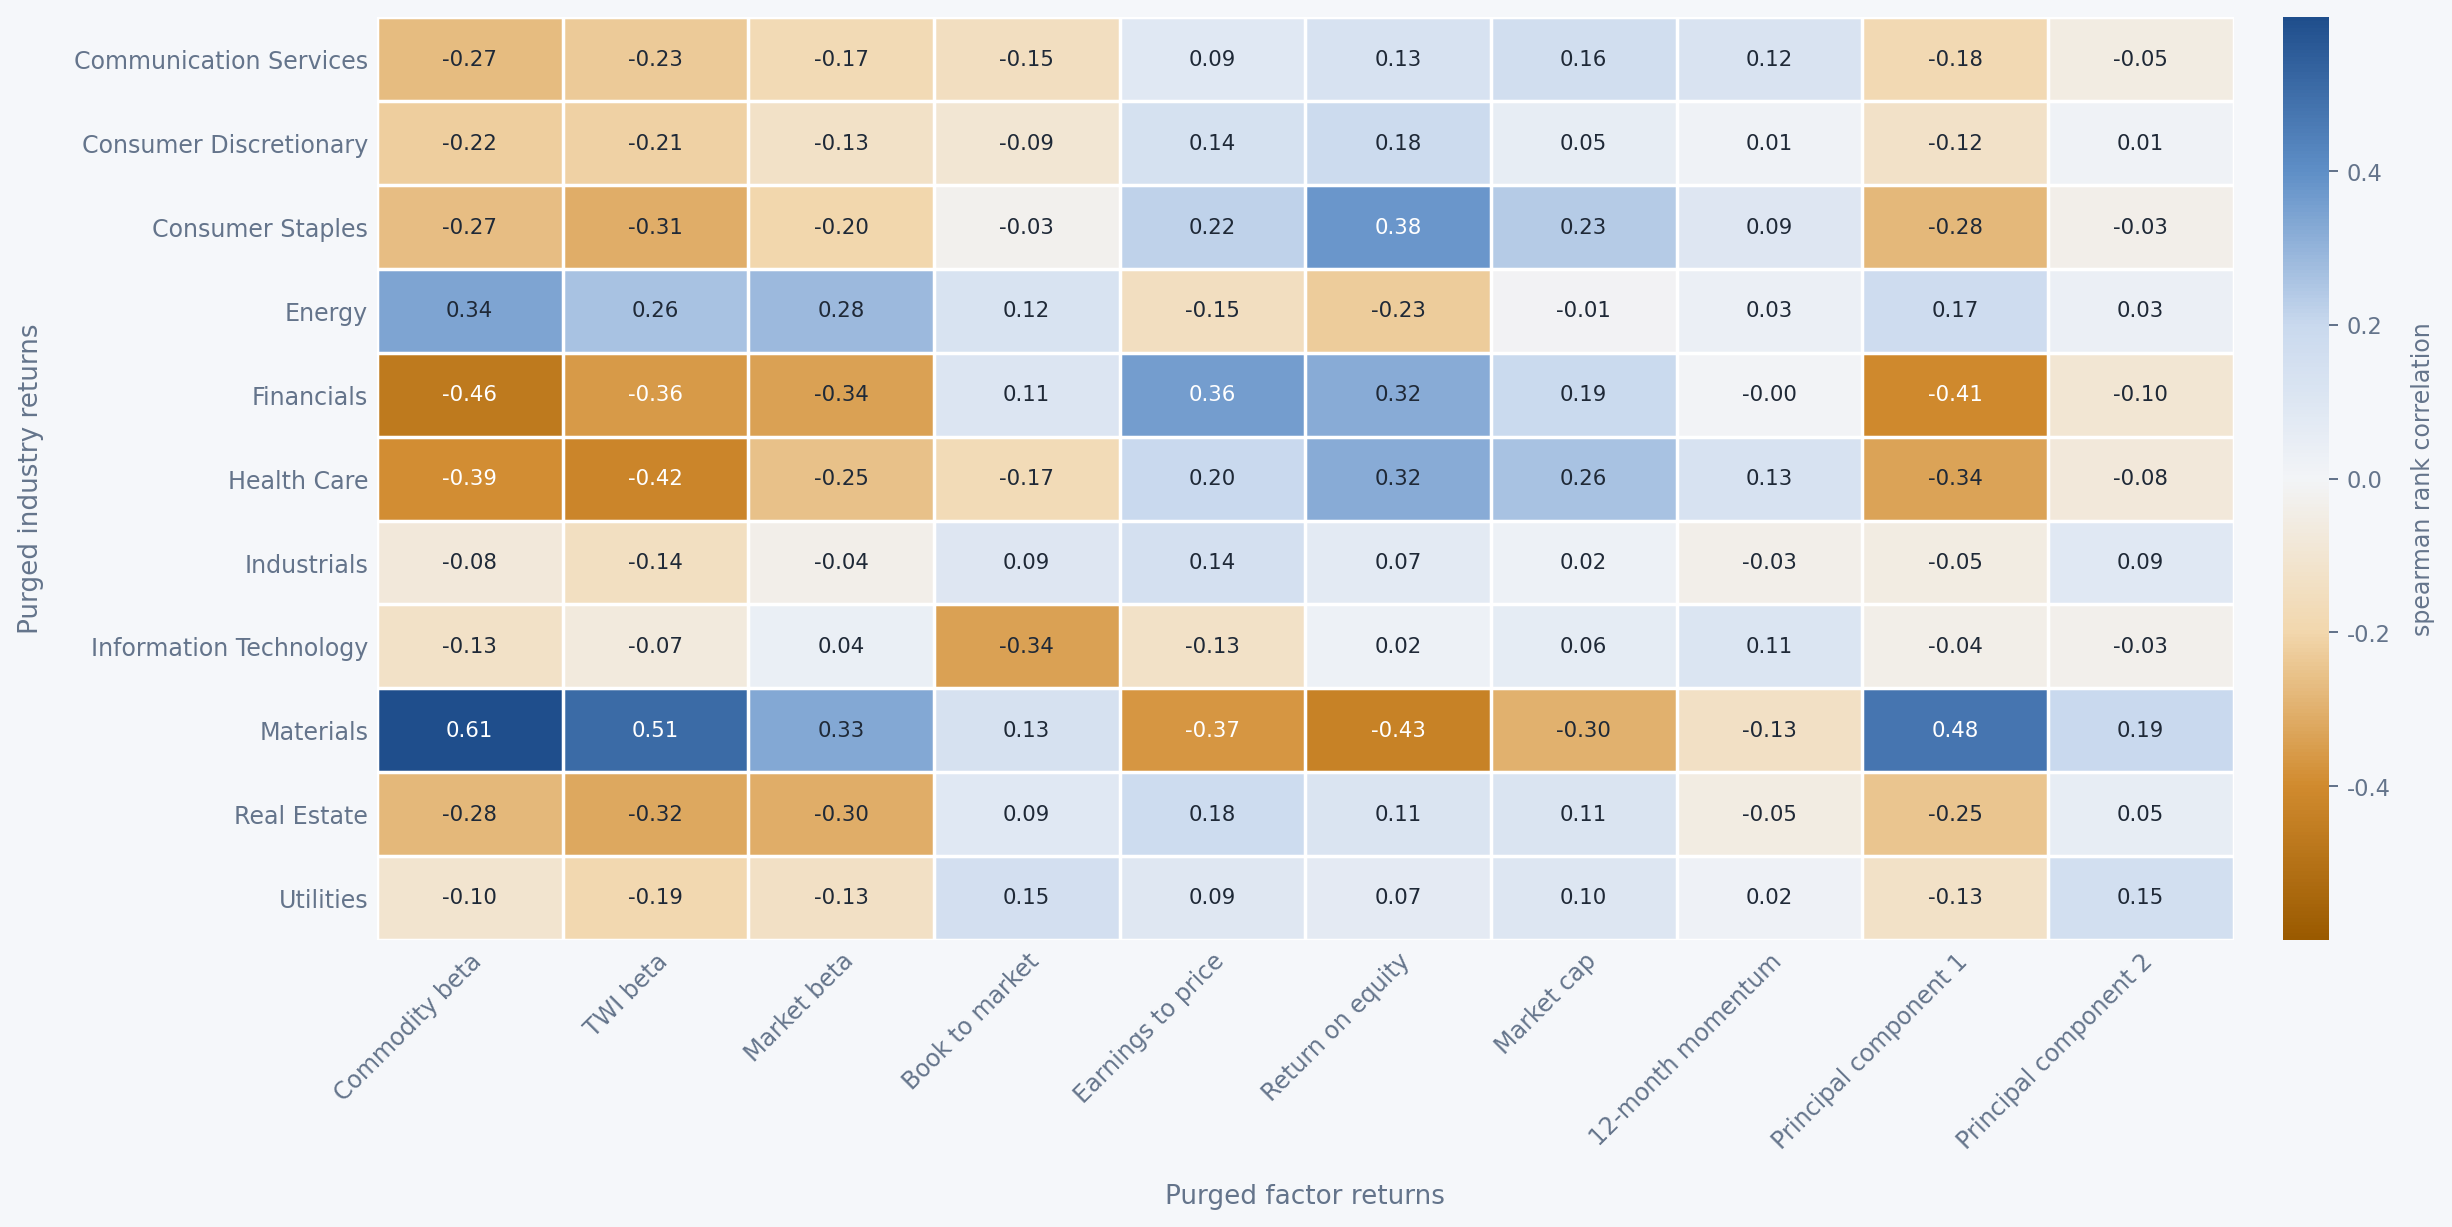
Here we present the rank-correlations between industry returns and the factor mimicking portfolio (FMP) returns for the shortlisted subset of observable factors. The returns of industries and FMPs have been purged of the influence of the market via time-series regression against the All Ordinaries Accumulation (total return) Index.
The purpose is to determine the extent to which apparently distinct factors are capturing similar return variation. High absolute correlations suggest overlapping exposures, while low correlations suggest more distinct sources of risk.
Interpretation
Removing the common market component materially changes the pattern of correlations and reveals more differentiated industry relationships. Commodity and TWI betas remain strongly positively associated with Materials and, to a lesser extent, Energy, but become negatively correlated with several other sectors, particularly Financials, Health Care and Real Estate. The broad positive relationship previously observed for market beta largely disappears, as expected once the common market component is removed, indicating that much of the raw correlation arose from common exposure to aggregate market movements.
Several fundamental factors also exhibit clearer sector structure after purging: earnings-to-price and return on equity are positively related to Consumer Staples and Financials but negatively related to Materials, while book-to-market remains notably negative for Information Technology. The first principal component continues to show substantial industry differentiation, whereas the second principal component and 12-month momentum remain comparatively weakly related to industry returns.